Category Archives: ETFS

Can Corn?

It’s January.  It’s cold.  And the ground in the Midwest is frozen (and getting more frozen by the moment I might #$%^ add).  So of course, it is time to thinking about planting corn!

Wait, what!?

Well, yes as it turns out just about everyone involved in the agricultural industry has questions (doubts?) about corn planting in the spring and the eventual crop harvested in fall.  And the big questions are, “How will planting go?” and “how much corn will be produced?”  As it relates to corm the whole supply/demand thing you learned about way back when hinges on the ultimate answers to those two questions.

In a nutshell, there is “doubt.”  No surprise really as there is absolutely not a single corn seed planted anywhere in the Midwest at this moment.  So, who knows for sure?

One thing we do know for sure is that a lot of people are aware of this phenomenon in corn and feel compelled to “hedge their bets”, typically on an annual basis.  Figure 1 displays an annual seasonal chart for corn futures from www.sentimentrader.com.1Figure 1 – Annual Seasonal trend for Corn (Courtesy Sentimentrader.com)
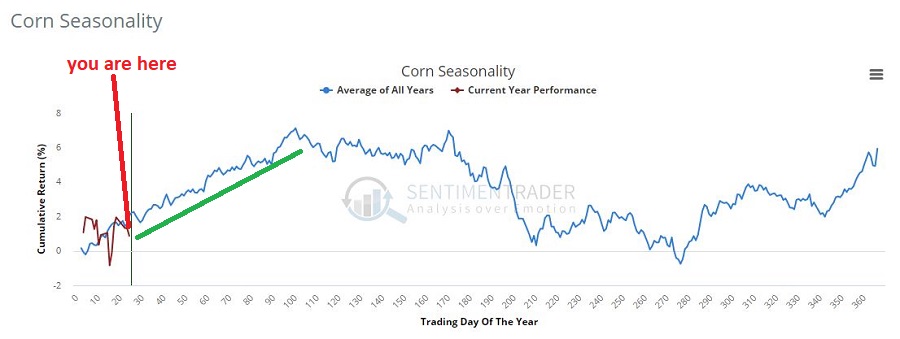
As you can see, price strength is typical in the first 4 to 5 months of the year.  This should not be surprising because – as I described above – doubt about supply causes buying pressure (typically).

So for traders the real question is “should I be buying corn in anticipation of buying pressure?”  The answer is “definitely, maybe!”  Let’s take a closer look.

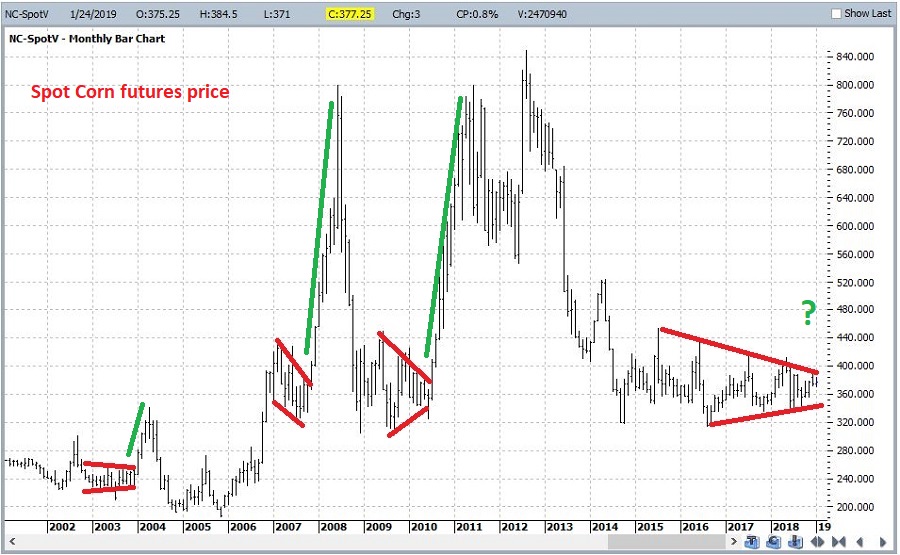
Figure 2 displays spot corn prices since 2001.
2

Figure 2 – Spot Corn prices (Courtesy ProfitSource by HUBB)

We can notice two things:

*Corn is presently in a fairly prolonged consolidation/compression range

*Previous consolidation/compression ranges have been followed by some significant advances

Despite this, one should not necessarily assume that corn is about to burst higher in price.  So let’s look at things from a more technical/tactical trading point of view.

How to Play Corn

*The “purest’ play is corn futures.  However, corn futures are not for most people.  In Figure 2, corn is trading at “350”, which equates to $3.50 a bushel in corn futures parlance.  Here is what you need to know:

If one were to buy a corn futures contract at $3.50 a bushel, a move to $4.50 a bushel would generate a gain of +$5,000 and a move to $2.50 a bushel would generate a loss of -$5,000.

In sum, a great way to make a lot of money if you are right and a great way to lose a lot of money if you are wrong.  There is an alternative for the “average” investor.

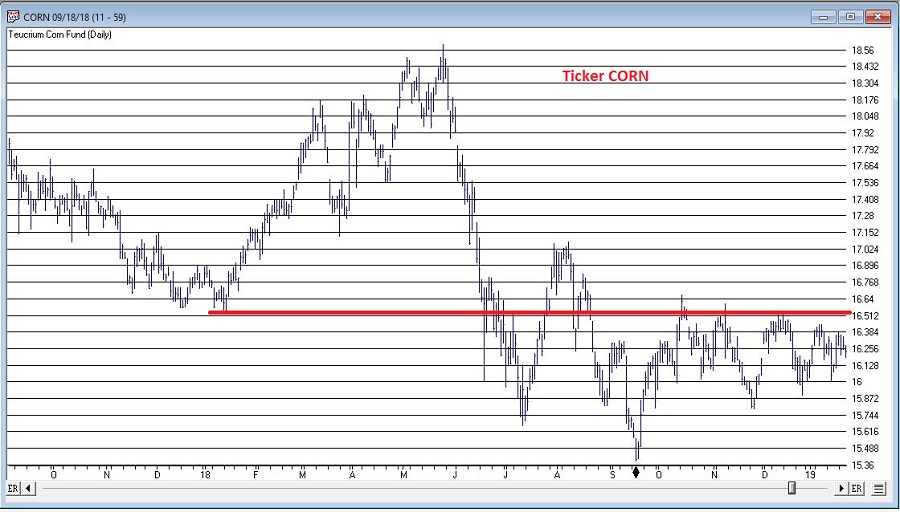
*Ticker CORN is the Teucrium Corn ETF which allows investors to trade corn like they would trade shares of stock.  Figure 3 displays a daily chart for ticker CORN.
3

Figure 3 – Ticker CORN with a significant resistance level around $16.53 (Courtesy AIQ TradingExpert)

Note that I have drawn a horizontal line $16.53, which connect the January 2018 low and the December 2018 high.  As with any line that one might arbitrarily draw on a bar chart, there is nothing “magic” about this price level.  But it does represent a potential line in the sand that be utilized in the following “highly complex” manner:

*CORN above $16.53 = (Possibly) Good

*CORN below $16.53 = Bad

The Choices

So what’s an investor to do?  As always, there are choices.

Choice #1 is flush this idea and forget all about corn.

Choice #2 is to buy now in hopes of an upside breakout, possibly with a stop-loss under the September 2018 low of $15.39.

Choice #3 is to wait for an upside breakout above $16.53 as confirmation that an actual bullish trend is forming.

Summary

I don’t make “recommendations” here at JOTM, so whether you prefer #1, #2 or #3 above is entirely up to you.  The key points though are:

It appears that there may be an opportunity forming (higher seasonal corn prices based on perceptions of problematic weather for planting and a long consolidation/compression in price).

A trader considering this idea needs to make decisions regarding what to trade (futures or CORN ETF), when to actually get in (before the breakout or after) and where to place a stop-loss.

Jay Kaeppel

Disclaimer:  The data presented herein were obtained from various third-party sources.  While I believe the data to be reliable, no representation is made as to, and no responsibility, warranty or liability is accepted for the accuracy or completeness of such information.  The information, opinions and ideas expressed herein are for informational and educational purposes only and do not constitute and should not be construed as investment advice, an advertisement or offering of investment advisory services, or an offer to sell or a solicitation to buy any security.
A Long and Short-Term Bond Market Perspective, Part I

Meanwhile, back in the bond market.  Yes, the stock market has been the place for “action” recently.  First a massive decline in short order followed immediately by a stunning advance.  But many investors also look to the bond market in order to achieve their long-term goals.  So, let’s try to put things in perspective a bit.

The Main Points

*Point A: Rates will likely work their way higher over time

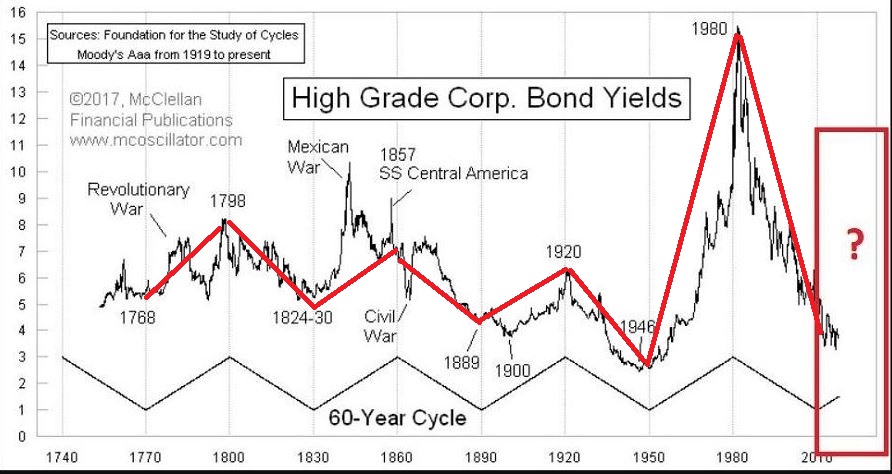
There has historically been a roughly 60-year cycle in interest rates (See Figure 1).  If this holds to form, odds are the next 30 years will not look anything like the last 30 years in the bond market, i.e., rates will likely work their way higher over time.

1

Figure 1 – 60-year cycle in rates suggest higher yields in years ahead (Source: mcoscillator.com)

*Point B: Investors should be wary of buying and holding long-term bonds

Figure 1 does not mean that rates will rise in a straight-line advance.  But again, odds are that rates will rise over time, so as a result, investors should be wary of buying and holding long-term bonds (as they stand to get hurt the most if rates rise).  That being said, in the short-term anything can happen, and long-term bonds may still be useful to shorter-term traders, BUT…

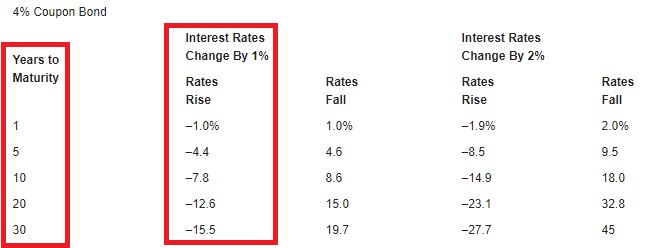
…Short to intermediate term bond funds are better now for investors than long-term bonds (if rates rise over time investors in short/intermediate term bonds can reinvest more quickly at higher rates, while long-term bond holders just lose principal).

4

Figure 2 – Affect of rising rates on bonds of various maturities (Source: AAII.com)

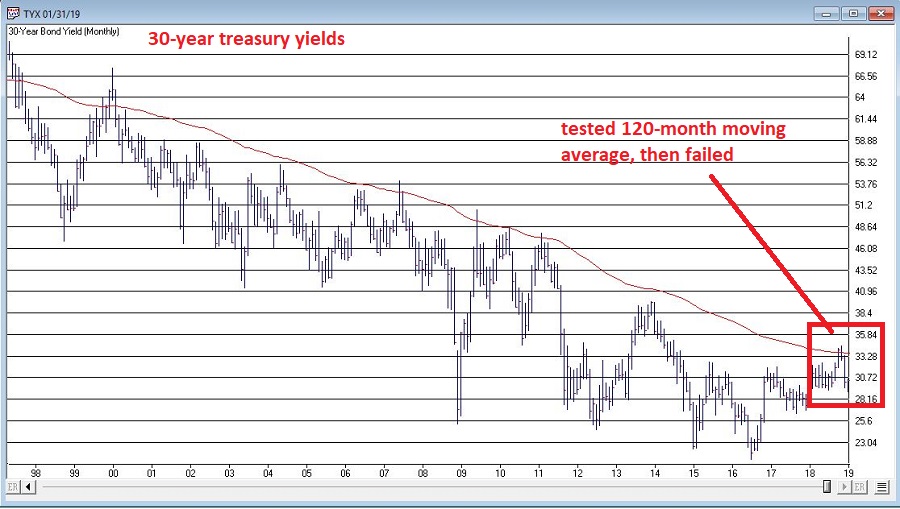
*Point C: It appears to be too soon to declare a confirmed “Bond Bear Market!!!”

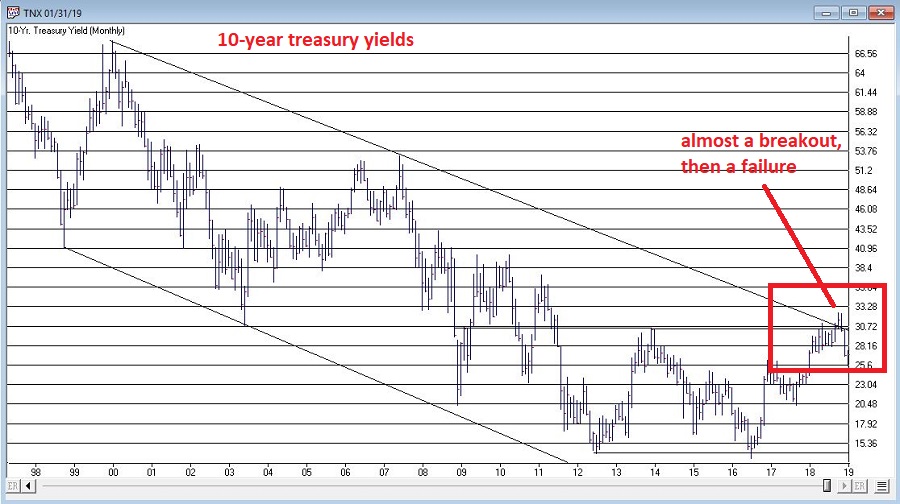
Bond yields looked in 2018 like they were staging a major upside breakout – and then reversed back to the downside.  So – Point A above not withstanding – it appears to be too soon to declare confirmed “Bond Bear Market!!!”

2

Figure 3 – 10-year treasury yield “breakout fake out” (Source: AIQ TradingExpert)

3

Figure 4 – 30-year treasury yield tested 120-month moving average, then failed  (Source: AIQ TradingExpert)

*Point D: Corporate bonds as a whole carry more risk than in years past

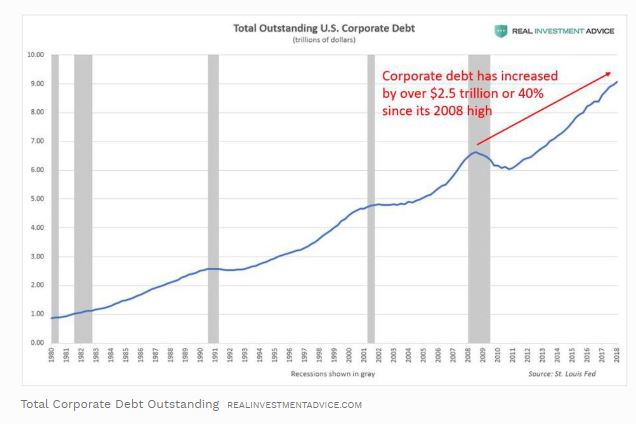
The risk associated with corporate bonds as an asset class are higher than in the past due to A) a higher rate of debt, and B) a large segment of the corporate bond market is now in the BBB or BBB- rating category.  If they drop one grade they are no longer considered “investment grade” and many institutional holders will have no choice but to sell those bonds en masse.  Which raises the age-old question, “too whom?”

For more on this topic see here, here and here.5Figure 5 – Rising corporate debt (Source: Real Investment Advice)

*Point E:

On the brighter side, two bond market models that I follow are presently bullish.  More about these in Part II.

Jay Kaeppel

Disclaimer:  The data presented herein were obtained from various third-party sources.  While I believe the data to be reliable, no representation is made as to, and no responsibility, warranty or liability is accepted for the accuracy or completeness of such information.  The information, opinions and ideas expressed herein are for informational and educational purposes only and do not constitute and should not be construed as investment advice, an advertisement or offering of investment advisory services, or an offer to sell or a solicitation to buy any security.
When to Buy Energy Stocks

Crude oil and pretty much the entire energy sector has been crushed in recent months. This type of action sometimes causes investors to wonder if a buying opportunity may be forming.

The answer may well be, “Yes, but not just yet.”

Seasonality and Energy

Historically the energy sector shows strength during the February into May period.  This is especially true if the November through January period is negative.  Let’s take a closer look.

The Test

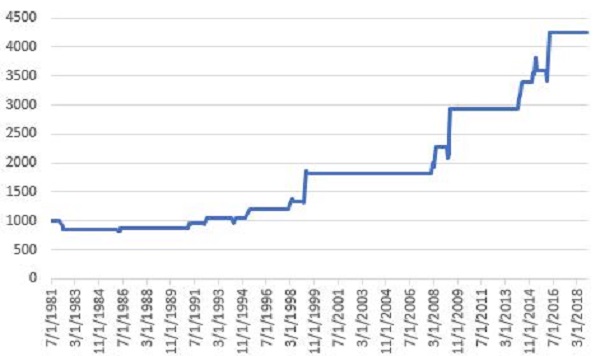
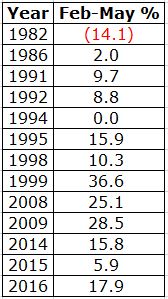
If Fidelity Select Energy (ticker FSENX) shows a loss during November through January then we will buy and hold FSENX from the end of January through the end of May.  The cumulative growth of $1,000 appears in Figure 1 and the yearly results in Figure 2.

1

Figure 1 – Growth of $1,000 invested in FSENX ONLY during Feb-May ONLY IF Nov-Jan shows a loss

2

Figure 2 – % + (-) from holding FSENX during Feb-May ONLY IF Nov-Jan shows a loss

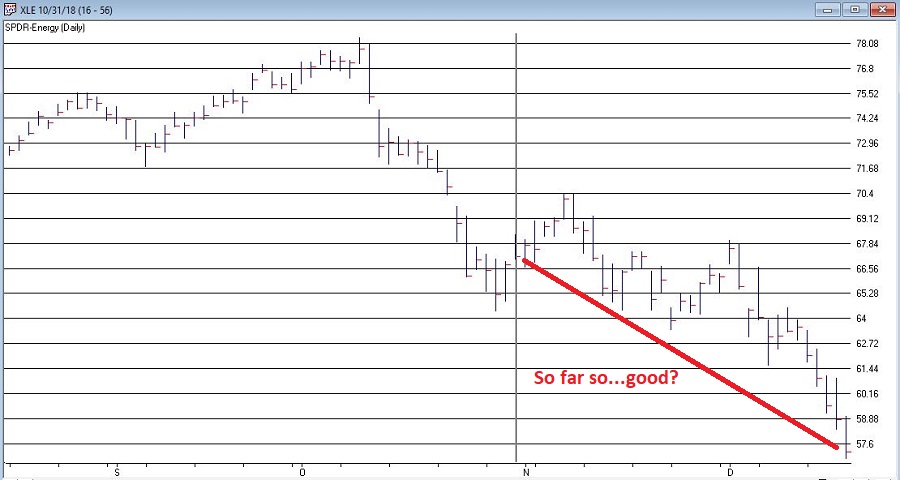
Figure 3 displays ticker XLE (an energy ETF that tracks loosely with FSENX).  As you can see, at the moment the Nov-Jan return is down roughly -15%.

3

Figure 3 – Ticker XLE (Courtesy AIQ TradingExpert)

All of this suggests remaining patient and not trying to pick a bottom in the fickle energy sector. If, however, the energy sector shows a 3-month loss at the end of January, history suggests a buying opportunity may then be at end.

Summary

Paraphrasing here – “Patience, ah, people, patience”.

Jay Kaeppel

Disclaimer:  The data presented herein were obtained from various third-party sources.  While I believe the data to be reliable, no representation is made as to, and no responsibility, warranty or liability is accepted for the accuracy or completeness of such information.  The information, opinions and ideas expressed herein are for informational and educational purposes only and do not constitute and should not be construed as investment advice, an advertisement or offering of investment advisory services, or an offer to sell or a solicitation to buy any security.
Focus on “Investing” (not “the Market”)

I don’t offer “investment advice” here at JOTM so I have not commented much on the recent action of the market lest someone thinks I am “predicting” what will happen next.  Like most people, predicting the future is not one of my strengths.  I do have some thoughts though (which my doctor says is a good thing).

The Big Picture

Instead of talking about “the markets”, let’s talk first about “investing”, since that is really the heart of the matter.  “The markets” are simply a means to an end (i.e., accumulating wealth) which is accomplished by “investing”.  So, let me just run this one past you and you can think about it for a moment and see if it makes sense.

Macro Suggestion

*30% invested on a buy-and-hold basis

*30% invested using trend-following methods

*30% invested using tactical strategies

*10% whatever

30% Buy-and-Hold: Avoid the mistake that I made way back when – of thinking that you should always be 100% in or 100% out of the market.  No one gets timing right all the time.  And being 100% on the wrong side is pretty awful.  Put some portion of money into the market and leave it there.  You know, for all those times the market goes up when you think it shouldn’t.

30% using trend-following methods:  Let me just put this thought out there – one of the biggest keys to achieving long-term investment success in the stock market is avoiding some portion of those grueling 30% to 89% (1929-1932) declines that rip your investment soul from you body and make you never want to invest again.  Adopt some sort of trend-following method (or methods) so that when it all hits the fan you have some portion of your money “not getting killed”.

30% invested using (several) tactical strategies: For some examples of tactical strategies see here, here, here and here.  Not recommending these per se, but they do serve as decent examples.

10% whatever:  Got a hankering to buy a speculative stock?  Go ahead.  Want to trade options?  OK.  Want to buy commodity ETFs or closed-end funds or day-trade QQQ?  No problem.  Just make sure you don’t devote more than 10% of your capital to your “wild side.”

When the market is soaring you will likely have at a minimum 60% to 90% of your capital invested in the market.  And when it all goes south you will have at least 30% and probably more out of the market ready to reinvest when the worm turns.

Think about it.

The Current State of Affairs  

What follows are strictly (highly conflicted) opinions.  Overall sentiment seems to me to be very bearish – typically a bullish contrarian sign.  However, a lot of people whose opinions I respect are among those that are bearish.  So, it is not so easy to just “go the other way.”  But here is how I see the current “conflict”.

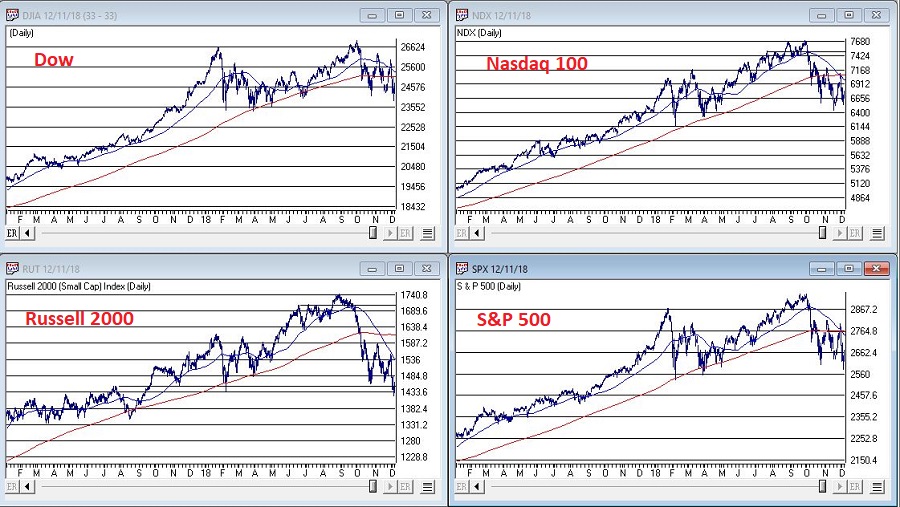
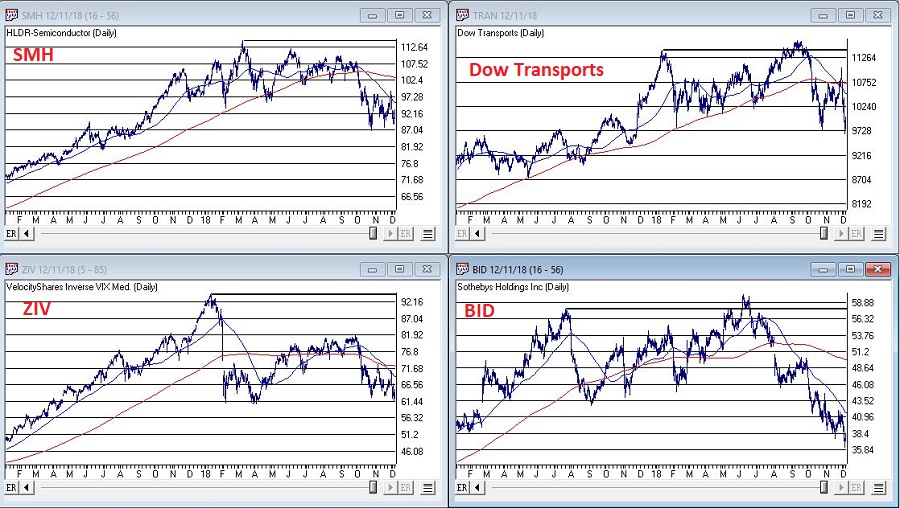
From a “technical” standpoint, things look awful.  Figures 1 and 2 show 4 major market averages and my 4 “bellwethers”.  They all look terrible.  Price breaking down below moving averages, moving average rolling over, and so on and so forth.  From a trend-following perspective this is bearish, so it makes sense to be “playing defense” with a portion of your capital as discussed above.

(click any Figure to enlarge)

1

Figure 1 – Major market averages with 50-day and 200-day moving averages (Courtesy AIQ TradingExpert)

2

Figure 2 – Jay’s Market Bellwethers with 50-day and 200-day moving averages (Courtesy AIQ TradingExpert)

On the flip side, the market is getting extremely oversold by some measure and we are on the cusp of a pre-election year – which has been by far the best historical performing year within the election cycle.

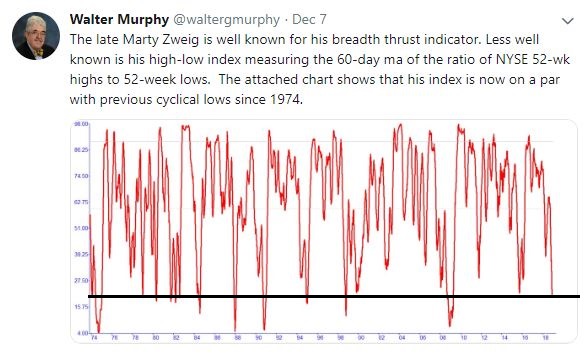
Figure 3 displays a post by the esteemed Walter Murphy regarding an old Marty Zweig indicator.  It looks at the 60-day average of the ratio of NYSE new highs to New Lows.  Low readings typically have marked good buying opportunities.

3

Figure 3 – Marty Zweig Oversold Indicator (Source: Walter Murphy on Twitter)

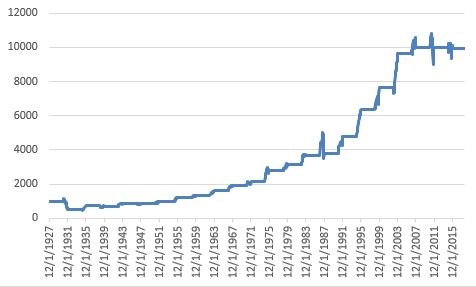
Figure 4 displays the growth of $1,000 invested in the S&P 500 Index ONLY during pre-election years starting in 1927.  Make no mistake, pre-election year gains are no “sure thing.”  But the long-term track record is pretty good.

4

Figure 4 – Growth of $1,00 invested in S&P 500 Index ONLY during pre-election years (1927-present)

There is no guarantee that an oversold market won’t continue to decline.  And seasonal trends are not guaranteed to work “the next time.”  But when you get an oversold market heading into a favorable seasonal period, don’t close your eyes to the bullish potential.

Summary

Too many investors seem to think in absolute terms – i.e., I must be fully invested OR I must be out.  This is (in my opinion) a mistake.   It makes perfect sense to be playing some defense given the current price action.  But try not to buy into the “doomsday” scenarios you might read about.  And don’t be surprised (and remember to get back in) if the market surprises in 2019.

Jay Kaeppel

Disclaimer:  The data presented herein were obtained from various third-party sources.  While I believe the data to be reliable, no representation is made as to, and no responsibility, warranty or liability is accepted for the accuracy or completeness of such information.  The information, opinions and ideas expressed herein are for informational and educational purposes only and do not constitute and should not be construed as investment advice, an advertisement or offering of investment advisory services,

The Two Most Important Bond Market Charts

A funny thing happened on the way that bond bear market.  But first the promised charts:
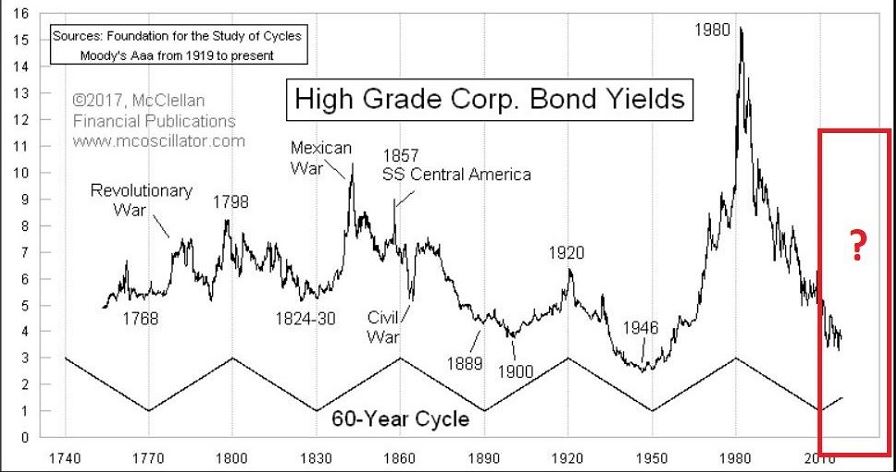
*Figure 1 strongly suggests that the next major move in bond yields is higher (as yields tend to move in roughly 30-year up and 30-year down waves).
1Figure 1 – 60-year bond yield cycle (Courtesy: www.mcoscillator.com)

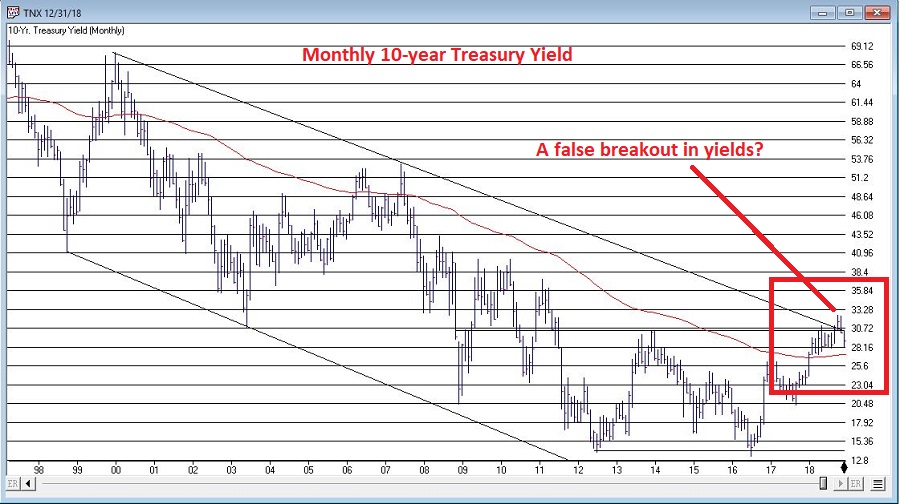
*Figure 2 displays the 10-year treasury note yield – with a long, long downtrend followed by an advance to a potential “fake out breakout” to the upside.  More to follow.
2Figure 2 – 10-year treasury yields (x10); ticker TNX (Courtesy AIQ TradingExpert)

Now for the recap:
*The 10-year treasury yield (TNX) topped out in the early 1980’s and declined to a low in July 2012.
*TNX then moved higher for about a year, then drifted lower to its ultimate low around 1.35 three years later in 2016.
*From there rates rose to roughly 3.25% by October 2018.  Along the way it took out its 120-month moving average, a horizontal resistance line at about 3.04% and finally a downward sloping trend line in October 2018.
*With “final resistance” pierced many bond market prognosticators assumed that yields were off to the races.
*And then that “funny thing” happened.  10-year yields fell from 3.25% in October to a recent level of roughly 2.90%.
At this point “predicting” where TNX is headed in the short run from here is pure conjecture.  There is a chance that rates will not rally anytime soon and that they may even continue to drift back lower.  Take your pick.  Flip a coin.  Whatever.  The bottom line is that what you see in Figure 2 is entirely in “the eye of the beholder.”
So let’s circle back to Figure 1.  The bottom line is this:
*The odds appear very good that the next 30 years in in bond yield will look a lot different than the last 30 years, when high grade bond yield fell from 15% to roughly 3% (which is OK, because if rates ever go negative and I have to pay the government just to hold my money I am going to be really pissed….but I digress).
*Short-term “traders” can trade long-term bonds to their hearts content.  However, “investors” may be wise to avoid long-term bonds.  Consider ticker TLT, the iShares 20+ year treasury bond ETF.  It presently has a 30-day SEC yield of 3.06% and an “average duration” of 17.42 years.  Here is how to understand that:
–Regarding yield, if price remained completely unchanged, and investor would theoretically earn roughly 3.06% in interest over the next 12 months
–Regarding duration, if interest rates rose one full percentage point, ticker TLT would theoretically lose -17.42% in value
Long-term bonds may rally from time to time.  However, for long-term investors holding bonds, this is NOT a favorable reward-to-risk tradeoff.
Summary
In the “big picture” we probably are in a long-term bear market for bonds.  But it may not look like it for a while.  So trade in and out as much as you’d like.  But for bond investment purposes I am keeping duration short.
Jay Kaeppel
Disclaimer:  The data presented herein were obtained from various third-party sources.  While I believe the data to be reliable, no representation is made as to, and no responsibility, warranty or liability is accepted for the accuracy or completeness of such information.  The information, opinions and ideas expressed herein are for informational and educational purposes only and do not constitute and should not be construed as investment advice, an advertisement or offering of investment advisory services, or an offer to sell or a solicitation to buy any security.